


Insights from experienced investors:
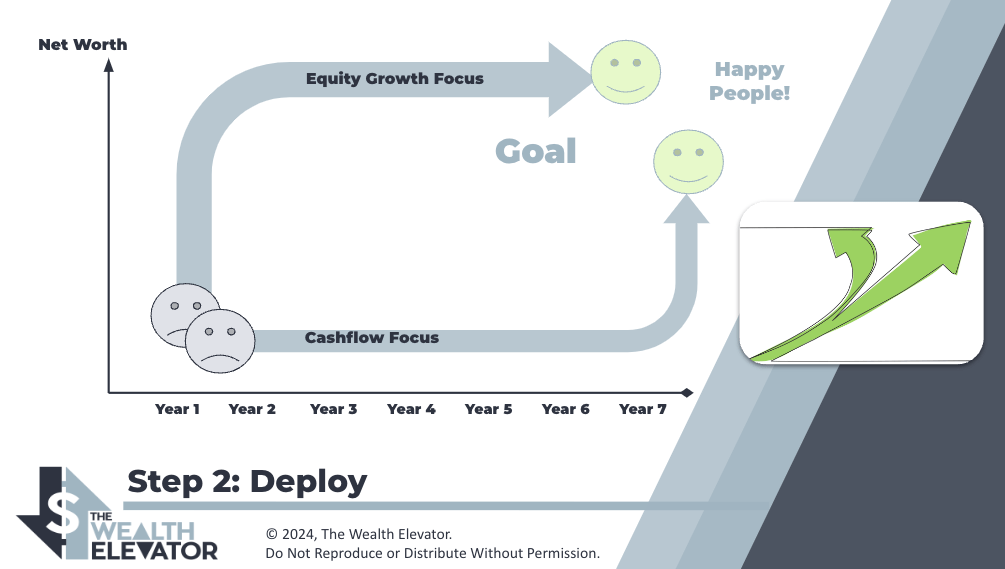
As stated earlier, newer investors will want to go for cash flow (vanilla), but after gaining some experience with a couple of deals when you see the deals dump out the retained equity in big chunks you might say “well crap, maybe I should have gone for the chocolate or swirl and made more money faster.” All in the positive progression of a passive investor 😁
Those under 1M-2M net worth, think in terms of monthly (example, all of the new and scared investors ask if pref equity is monthly because they need that monthly income for peace of mind), but higher net worth or Family Office money think in terms of quarterly, annually, or longer.
On the surface, the vanilla is the “safer” deal, but in reality, the safer play could be the unique deal whether it was the Chocolate or swirl investment options that had a special aspect like a heavy loss to lease play, hedged with a great submarket or a development project, where you are building it at 60% of the sale price (ie development).
Other ways others look at these deals:
- Looking at each deal through the lens, “What is the worst that can happen here?” The more perceived risk you take on the more potential returns or cone possibilities.
- Look at it from a geographical diversification perspective first, see where you are heavier or lighter.
That’s what I really value knowing: what are people with similar net worths to me doing?
These are the conversations that happened in Hawaii for HUI4 and on the one-on-one calls that FOOM members have throughout the year. I don’t claim to have the answers, but I am always trying to learn what the next shelf of people are doing to compress the learning curves, like how we prevent 1M folks from buying a bunch of SFH rentals. But this is where things get personal… You have a business where some are more W2 salaries, plus some people have different end goals and lifestyle visions.
Thanks for that. In that analogy, I definitely want to tee up more “swirl” type deals compared to the “vanilla” ones. I just didn’t know what might be most advisable for me.
At the end of the day… It’s all ice cream, and this stuff we are investing in is real hard assets that, at any point (should a recession come), have enough money in the capital plan to go to a cashflow and hold position.
I’ve watched the video on DEALABC, so my only question was, when do you know it’s time to turn off the music? I get the idea is to buy, sell, buy, repeat, but when to determine when that final sale is the time to cash out? After reaching 7X?
From an operator on the deal level, we keep going down the road for 2-3 rollovers and wait for some opportunity in the tax code to open up to jailbreak the gains or we might simply put into a long term low return triple net deal or return your money… we don’t know but we are all aligned… no one wants to pay taxes. This is why we take a smaller number of investors into these who already trust us, because as you know, the longer a marriage goes things will change, and it is better if everyone is aligned for the end goal. On this particular deal, the sponsors make that decision when it is the best time to exit.
From your personal side, this is, of course, one part of your portfolio. 2-5% call it that, and therefore you should be semi-disinterested as it is just a small part of the whole.
Do you have a “chocolate” in Texas or elsewhere in the South that is open now to receive funds?
You will be waiting a very long time for that. Chocolate deals are very rare because of the rare land that makes sense from a use and price standpoint. This is an opportunity to grow the team to go after more in the future.
How to Offset Returns on This Amazing Deal We Just Exited
Here is a more recent video talking about depreciation recapture.
This is a quick rundown on the tax implications and the use of your passive losses to roll that capital gain depreciation recapture forward.
Selling other assets? Access our Masterclass: 8 Ways to Eliminate Capital Gains for Accredited Investors
Talk it through with us
Questions on “Getting Started” as you look at real deals? Join The Wealth Elevator investor community and bring them to your onboarding call.
Join the club and book your onboarding callJoining is free.

The podcast behind this course
The Wealth Elevator Podcast
Lane's show for accredited investors on passive syndications, taxes and alternative investments. Many of the lessons in this course started as episodes.
Listen on Apple PodcastsWatch on YouTube