


Syndication FAQs
Below are some frequently asked questions regarding real estate syndication.
Why is the limit of non accredited investors 35?
In short, it’s just another strange rule that governs 506B real estate syndication offerings. You can read Rule 501(a) of Regulation D promulgated under the Securities Act of 1933 (the “Securities Act”). Here is my best attempt at explaining this… An accredited investor is defined by the United States Securities & Exchange Commission as someone who makes a minimum of $200,000 ($300,000 if filing jointly) or has a net worth of 1 million dollars excluding personal residence. The significance of being an accredited investor is that you can invest in things that those with less money cannot. You can also be something called “a sophisticated investor” which has a much more nebulous definition but essentially says you know what you are doing even if you don’t have that much money. A 506b offering allows 35 non accredited investors who must be “sophisticated investors.” These laws were put in place long ago to “protect” the average passive investor from predatory activity. The irony of this all is that there is no protection for the average individual investor, or pension funds for that matter, against investing in a wildly bloated stock market at record valuations. Every major trader out there knows we are in a bubble but there is no protection for individuals dumping money into their retirement accounts to buy mutual funds. It’s an archaic system which makes little sense. Certainly, there has been some recognition of this fact. The 2012 JOBS Act made it easier for Main Street America to participate in “alternative” investments via crowdfunding and made it easier for sponsors to advertise a previously unknown syndication opportunity on social media. However, we have a long way to go. I would advise you that you need to know the lead general partner personally. None of this “We met at a local REIA and he pitched me his deal”. If a guy does not have a list of solid investors, they must lack the track record.
How come I have to do this third-party certification for this Reg D 506C investment?
It all depends on what the syndicator does to market the real estate syndication deal which determines if the deal is a 506B or 506C.
506C allows for open marketing and general solicitation, but the SEC wants to protect the average non accredited investor from doing something dumb so only Accredited are allowed. Thus the 3rd party check.
506B is not openly marketed, and thus there is a little less scrutiny from the SEC. But as the syndicator, I have to act responsibly because if I make the wrong call, you could get all your money back. Of course, this is all predicated on the deal going south and as in sports… winning (a good investment) covers up a lot of things.
What is the minimum investment?
Typically, I see $50,000 as the minimal investment in 90% of deals I take a look at. Sometimes you can find $25,000 deals, but those are typically done by newer syndicators. Asking to get a lower minimum just to get a “good deal” is annoying and can be poor form.
The GP wants to minimize the number of investors and keep it to 40-100 investors per deal. The more investors mean more headaches, filing costs, etc.
Institutional operators with higher acquisition fees and worse LP splits usually are around $100k-250k+ minimums. Sometimes a sponsor will have the flexibility to lower the minimums, but it can be bad form to always be that LP who is asking to get in for less. It is the equivalent of that guy who is always asking for a discount and the first guy left off the roster when the deal fills up. Remember that this is a relationship business.
Is $100k enough liquidity for a non-accredited investor?
This is a guide, not a rule. Think about it – $100k will be gone in a couple of deals at $50k per investment. If you don’t have adequate cashflow coming in annually (~$30K a year), you are a sitting duck for a year or two. I would think of this as using SFHs to get you from gear 1-2 or 0-35mph in a car. People who have excess money after expenses (Cashflow) via their day job or investments (Gear 5-7 or over 55 MPH) should transition to syndications at some point for diversification and scalability if they are NOT a good operator. If they are, they should syndicate and lead deals. This transition is tricky. Yes, it’s a little uncomfortable.
It is recommended that you understand the business. Starting small with at least one SFH is recommended as a prerequisite to getting started with bigger investments. Although finding and working with good operators is great, unfortunately, good operators do go into bad deals. Also, you want to be able to have a surface-level idea of what is in these executive summaries of these offerings.
Where can I find syndication deals?
Most deals that are NOT public (506B) but most people who don’t have a network can only see the mass-marketed 506C deals for accredited investors only (via Crowdfunding websites). If you are a non-accredited investor, you will need to put yourself out there and start shaking hands or picking up the phone (or post-pandemic get on a Zoom call). Real estate, especially syndications, is a people-based investment.
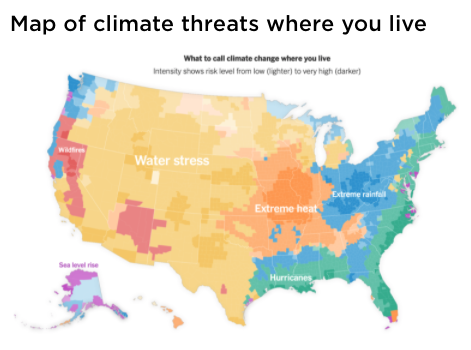
What Happens if there’s a Natural Disaster?
Flood Zones
Be careful of investing in properties that fall in the FEMA 100-year flood map. Insurance can help mitigate a loss, but this is something to check on your own.
Deeper Learning
Understanding 506(b) vs 506(c) Deals [VIDEO]
Understanding 506(b) vs 506(c) Deals [ARTICLE]
I do prefer development over stabilized deals because of the bigger upside. I do understand there is more risk but we are still in our 40s and can recover from losses. When we get into our 50s can we shift over to more stabilized deals?
I do agree in the RIGHT syndications (it’s really hard to tell how fat or lean a deal is from an LP perspective) the risk is well worth the reward.
Learning how to underwrite single-family homes is a good start.
And I totally get it. Your current day job income more than makes up for your daily expenses and you have good job security (those are two prerequisites I always ask investors when they are interested in no cashflow/development type deals).
But for you guys knowing your situation, I would try to get $2-4k of passive income coming in per month so at 8% cashflow that would require around $500k invested into stabilized deals (not including AHP). I see AHP as sort of a short-term solution; plus, it’s ordinary income (booo). Once you have that minimal base, then go after more developments and try to open it up and take more risks (i.e. going after more home runs).
Cashflow does amazing things – like freeing up mental headspace, allowing us to breathe freely and be happier. I would prefer you get that ASAP instead of holding your breath with 50% more long-term plays. In the end, whether you 2x your money in 3 years or 5 years (with cashflow along the way) you are doing an amazing job. And when you combine that with the passive losses, real estate professional status, and other tax strategies, you are looking at retiring in 5-10 years as opposed to the conventional 30-50 years.
Another side note with stabilized cashflow assets (built after 1970 or newer and in good areas), the business plan lines up to be more of a long-term or legacy hold which is another thing that a high-income earner needs to pay attention to. Say you double your money in 3 years with a development but the asset is sold off, well you would have to take your tax hit then. Compare that to a deal that gets refinanced several times and is held for a decade or more… you delay that tax bill. Might not matter if you are swimming in $500k plus in passive losses, but something to be aware of.
Also along these lines, don’t make the mistake of looking for a Class C, high cashflow deal. Proformas are just proformas and Class C tenants don’t really pay and those deals tend to not cashflow as advertised and the sponsors will likely sell it within 3-5 years due to the headaches involved with bad areas. That means you are looking to pay that tax bill early.
What’s the (economic) vacancy rate for the submarket?
Usually, you plug in 10% for a regular market and 8% for an Atlanta/Dallas (hotter market). After that, you deduct a few percent points to account for deadbeats (economic vacancy). In the end, this moves the needle very slightly. The Cap rate is the biggest factor on proformas – i.e., what you use for the reversion cap rate.
What’s the Crime Rate? (Example Answer)
- The current property manager who has managed for the last 2 years has cited that crime is not bad on the property, there has just been a notable incident which was not residents, but outside instigators.
- Residents are thoroughly screened with appropriate background checks, etc.
- We’ve also called the local police department to corroborate.
- We will be installing security cameras. We’ve also been on-site; you don’t need a bulletproof vest to walk around.
- I’ve driven there at night, and there’s plenty of lighting thanks to recent LEDs installed, and no issues.
Talk it through with us
Questions on “FAQ and More” as you look at real deals? Join The Wealth Elevator investor community and bring them to your onboarding call.
Join the club and book your onboarding callJoining is free.

The podcast behind this course
The Wealth Elevator Podcast
Lane's show for accredited investors on passive syndications, taxes and alternative investments. Many of the lessons in this course started as episodes.
Listen on Apple PodcastsWatch on YouTube