Looking for a good CPA or SDIRA Vendor?
If you would like a referral to the teams that we use please click this button, complete the form, and we will be in contact with in 2-3 business days.

How a Solo 401(k) or self-directed IRA lets you hold private investments, what it costs, and why I chose not to use one myself.
A qualified retirement plan (QRP) is a tax-advantaged account built for retirement. A 401(k) from your employer is one. A Solo 401(k) is the version for people with self-employment income and no full-time employees other than a spouse. A self-directed IRA (SDIRA) is an IRA held at a custodian that allows assets outside the stock market.
With a Solo 401(k) or SDIRA you can hold private real estate, private credit and other private investments inside the account. The gains stay tax-deferred, or tax-free in a Roth, as long as the money stays in the account and you follow the rules.
The trade-off is access. In most cases you pay a 10% penalty plus income tax if you take money out before age 59 1/2.
Most of the people who ask have a large balance in an old 401(k) or IRA and very little outside it. They are accredited, they want to diversify into private investments, and the retirement account is where most of their money sits.
If that is you, there are three paths I see people take. Each has a cost.
It is the simplest choice and it costs nothing to set up. Your choices are limited to the funds your plan or brokerage offers, so this money stays in public markets.
This lets the account itself invest in private deals. What to know before you do it:
This is what I did. I cashed out my own 401(k) years ago. My reasons were personal: I wanted access to the money well before retirement age, I expected my own tax rate to be higher later, and I wanted investments where the depreciation could be used on my tax return.
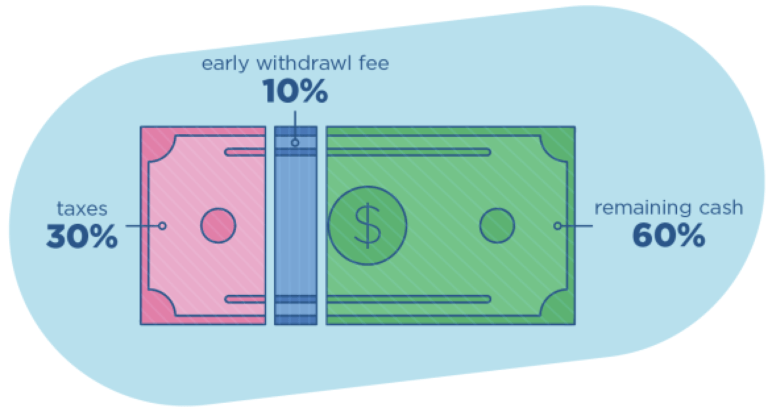
It was expensive. A withdrawal before 59 1/2 is taxed as income and usually carries the 10% penalty. On a $100,000 withdrawal, someone in a 25% federal bracket and a 7% state bracket would owe about $25,000 federal, $7,000 state and $10,000 in penalty. Your brackets will be different, and a large withdrawal can push you into a higher one.
Some people spread withdrawals over several years to keep their income from jumping. Whether that makes sense depends on your age, your income, your state and what you would do with the money. This is a decision to make with your CPA, with the numbers in front of you.
The IRS lists exceptions. The common ones:
Hardship withdrawals from a current employer’s plan are a separate rule. The plan has to allow them, the need has to be “immediate and heavy” under IRS rules, and most are still taxed and penalized.
This is a list for reference. I am not recommending any of them. Most of the time we are not paid for referrals. If that changes for a provider, we will say so.
401kCheckbook
Accuplan
Advanta IRA
American Estate & Trust
American IRA
American Pension Services (defunct)
American Trust Retirement
Asset Exchange Strategies
Broad Financial
Cambridge Retirement Services
CamaPlan
Capital IRA
Central Bank (may not currently support self-directed IRAs)
Checkbook IRA
Community National Bank
Crowdfund IRA
Digital Trust Company
The Entrust Group
Equity Institutional
Equity Trust Company
First Trust Company of Onaga
Financial Trust Company
Forge Trust Company (formerly IRA Services Trust Company)
GoldStar Trust Company
Guidant Financial Group, LLC
Horizon Trust Company
iPlanGroup
IRA Advantage
IRA Club
IRA Express, Inc.
IRA Financial Group
IRA Innovations
IRA Resources (merged with New Direction Trust Company)
IRA Services Trust Company (merged with Forge Trust)
IRAvest
Kingdom Trust Company
Lincoln Trust Company (now part of Millennium Trust Company)
Madison Trust Company
Mainstar Trust
Midland IRA
Millennium Trust Company
Mountain West IRA
MyEquity IRA
Nevada Trust Company
New Direction IRA (now New Direction Trust Company)
New Standard IRA
Next Generation Trust Services
Nexus Direct IRA
NuView IRA
Pacific Premier Trust (formerly PENSCO)
Peak Trust Company
PGI Agency
PolyComp Trust Company
Preferred Trust Company
Premier Trust
Provident Fiduciary Trust
Provident Trust Group
Quest Trust Company (formerly Quest IRA)
RealTrust IRA Alternatives
Safeguard Advisors
Self Directed
Self Directed IRA Services, Inc. (merged with Mainstar Trust)
Sense Financial
Sovereign International Pension Services
Specialized IRA Services
Summit Trust Company
SunWest Trust Company
The Self-Directed IRA Graveyard
Trust Company of America (acquired by ETRADE and now ETRADE Advisor Services)
uDirect IRA
Vantage
If you would like a referral to the teams that we use please click this button, complete the form, and we will be in contact with in 2-3 business days.
I am not against retirement accounts. I think they are tools that fit some situations better than others. For a high earner with a large balance who is close to retirement age, keeping the money in a Solo 401(k) or SDIRA and investing from there can make sense. For someone younger who wants access to the money, the math can point the other way. I cannot tell you which one you are. Your CPA can.
Yes, if it is a self-directed IRA and the sponsor accepts retirement accounts. If the deal uses debt, expect UDFI and a possible UBIT bill inside the IRA. Ask the sponsor and your CPA before you invest.
A Solo 401(k) is generally exempt from UDFI on real estate debt and an IRA is not. You need self-employment income to open one.
No. Losses stay inside the account.
No. Since January 1, 2018, a Roth conversion cannot be recharacterized.
Many plans allow a loan, generally up to half of your vested balance with a $50,000 cap, repaid through payroll. Check your plan’s rules and what happens to the loan if you leave the job.
If you want to talk through private investing with other accredited investors, join the community at theWealthElevator.com/club.
Lane Kawaoka, PE, is the founder of The Wealth Elevator and the author of two Amazon bestselling books, The Wealth Elevator and Simple Passive Cashflow. He spent 12 years as an engineer, bought his first rental in 2009, and left his job in 2019. He built his base in real estate and today is a general partner, operator and fund manager working with a community of accredited investors across real estate, oil and gas, and private companies. His track record: $2.1B of past real estate acquisitions, 10,000+ units acquired, 65+ projects, and $230M+ raised.
This site is free education for accredited investors and high-income professionals whose net worth sits mostly in stocks, a 401(k) and a salary. Start with the guides, the podcast or an event.
This is educational content, not tax, legal, or investment advice. We are not attorneys, CPAs, or financial planners. Please let us know if you need a referral to a CPA, lawyer, or other vendor here.
