
Private Money Lending
What is Private Money Lending?
There’s no doubt that real estate investing is astute and it can be highly remunerative for anyone given the property foundation, network, and learning. It is highly advisable for real estate investors to be smart and prudent with their money. Yes, as an investor you have the ability to reinvest into numerous real estate properties using a traditional loan but finding another option will not be bad after all.
Private lending isn’t the most popular option investors take, however, it offers securities and promising profit as with real estate investing.
Private lending can be confused with hard money lending as both can be used as alternatives for traditional financing to secure an investment property. Private lending tends to be more flexible than getting a hard money loan in terms of regulation, lending criteria, and experience. Hard money lenders are typically companies or an institutional lender rather than individuals, are more experienced, are regulated by state and federal lending laws, and have stringent lending terms.
Why Be a Private Money Lender
Rather Than Take on a Conventional Loan?
Private lending isn’t the most popular option investors take, however it offers securities and promising profit as with real estate investing.
What are Some Advantages of Private Money Lending?
Private money lending happens when an individual lends his own capital to be borrowed by another investor while procuring the loan with a mortgage (real estate). In reality, private money lending provides a substitute for conventional lending institutions like banks.
Start Earning Passive Income
with Institutional-Grade Senior Debt
Join a fund designed for capital preservation and consistent cash flow, with first-lien protection.
Private money lending allows you to safely generate “mailbox” money, secured by title to real estate collateral! This is about as passive as it gets!
A private lender provides capital to professional real estate investors for the purchase of real estate or to supplement funds for covering down payments, renovation costs, or closing costs. This is also known as mortgage lending, peer‑to‑peer lending, self‑directed lending, and non‑traditional lending.
This is a way of cutting out the middleman making it a win-win for the investor and borrower (flipper). Private money loan investors are given a first‑line position mortgage and promissory note that get recorded at the county courthouse, making this a secure, collateral‑based investment.
This is your opportunity to be completely hands-off while partnering with people I know, like, and trust.
No need to worry about tenants, buyers, or contractor hassles!
Compared to a traditional bank loan for a real estate investment, the loan term can sometimes be negotiated. This will depend on how the loan amount, the higher the loan amount, the more negotiating you can do with the interest rate you receive.
What are the Normal Terms for Private Money Lending?
If someone offers you a 12-15% interest rate does not mean it’s a good deal. The sucker could be you!
Think about it! Will a reliable operator with a good track record pay investors more than 8-10%? Most people in my mastermind group that I am part of, borrow money at 5-8%.
Below are some basic private loan guidelines but be aware that Cap rates go up and down from time to time based on the Fed rates.
BASIC GUIDELINES
Lower Risk: 1st Lien loans up to 80% of the Purchase price & 70% AS IS value (what you could realistically sell for now)
- 2-3 points
- 10-12% annual rate
- Average loan amount = 75% of the purchase price loan
- Target annualized ROI = 16-24%
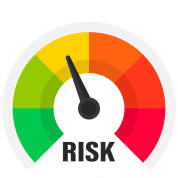
Moderate Risk: 1st Lien loans up to 70% of ARV
- 4-6 points
- 18%+ annual rate
- Target annualized ROI = 28-36%
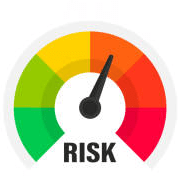
Moderate-High Risk: 2nd Lien loans up to 75% of ARV
- 7-15 points
- 18%+ annual rate
- 1st + 2nd liens up to 75% of ARV
- Target annualized ROI = 40-50%
Note: There are a lot of outfits out there that find a newbie house flipper and “white-labels” that person’s high-risk loan as their own. Don’t be fooled by this game!
Most reliable flippers can complete a project in 4-6 months from purchase to sale. A good rule of thumb for construction is that crews will work at a burn rate of $1,000 per day.
Looking for a good
CPA or Lawyer?
Skip the guesswork — we’ve done the research and made the connections.
Just submit a quick request through our form, and we’ll match you with trusted CPA or legal professionals tailored to your needs.
How are These Deals Funded?
✔️ Traditional and Roth IRAs, Pensions, SEPs, Solo401Ks, and other retirement accounts
✔️ Lazy cash sitting in the bank
✔️ By liquidating unsecured investments such as stocks
✔️ Solo401ks or other QRPs
✔️ Leveraging their Homes Equity at 4% to earn generous returns via a HELOC
✔️ Personal and Business Lines of Credit to arbitrage the interest rates
Most commonly, private lenders seek to maximize investment returns in exchange for speed and flexibility—funding traits that are highly sought after by real estate investors.
Becoming a private money lender is a rare opportunity to cut out the middleman and become the bank while safely generating a consistent flow of monthly income.
Clients who lend us money profit just as any bank would, but at a higher rate of return. We pay our lenders anywhere between 8 and 12% interest on their capital depending on the loan terms and debt coverage.
How Do These Deals Receive Financing?
STEP 1 – Your funds go into escrow with a licensed and experienced attorney and title company.
STEP 2 – Costs associated with finalizing the paperwork and doing everything formally are covered by us.
STEP 3 – You receive a copy of the original promissory note, a copy of the mortgage, and proof of the insurance policy. This is your collateral in case we do not perform and you can take the property back.
STEP 4 – The mortgage and promissory note are filed and recorded at the courthouse.
STEP 5 – You get your interest just like a bank charges you, except this time you are the bank!
What are the TOP MISTAKES
in Private Money Lending?
1. Never buy a note on something you wouldn’t want to own. Consider the worst-case scenario where if your borrower defaults you take it over. You might need to have a team there or some contacts local that you trust.
2. If the loan goes into default, take action immediately and start the timeline just like an eviction.
3. Do not loan money to someone you would feel uncomfortable foreclosing on such as a friend or relative.
4. If you are lending money on repairs you might want to originate a separate note with a higher interest rate with separate collateral so as to not encumber the original asset with debt that puts you in a lower leverage position if you ever have to collect.
5. Beware of borrower robbing Paul to pay Peter. Collect monthly installments so you know if the borrower is getting into financial trouble.
6. If you don’t know what you should get in terms of interest rate or don’t know how to evaluate the risk get a mentor or hire a 3rd party professional who will give you their opinion of the deal. Don’t do a sucker deal even if they are offering you 12-15%+.
7. Get lender’s title insurance for the loan. The purpose of title insurance is to shift risk away from you to the title company when creating a real estate note.
8. Verify that there is property insurance on the deal and that you are named as an additional insured. Even though it’s a remote chance of any issues it costs very little to have you covered. Plus you as the lender often has more to lose than the flipper.
9. Insist that the borrower provide you with evidence of payment when property taxes, insurance, and homeowner’s association fees become due and are paid, or when possible have your loan servicer set up escrow service to pre-collect the required funds.
10. Get a personal guarantee if you are lending to an entity or to an individual with some weakness. Or, have the borrower execute a Deed in Lieu (DIL) of foreclosure and send it to you or your custodian. Should the borrower default, you can record the DIL to save the expense and time of foreclosure.
What are the cons of private money lending?
1) No exit strategy – If I am going to do private money lending I am going to do it in an area (secondary or tertiary) and non-luxury class (Class B or C) where I can achieve a 1% Rent-to-Value Ratio or more. So if the economy corrects during construction I can rent the property out and not bleed holding costs.
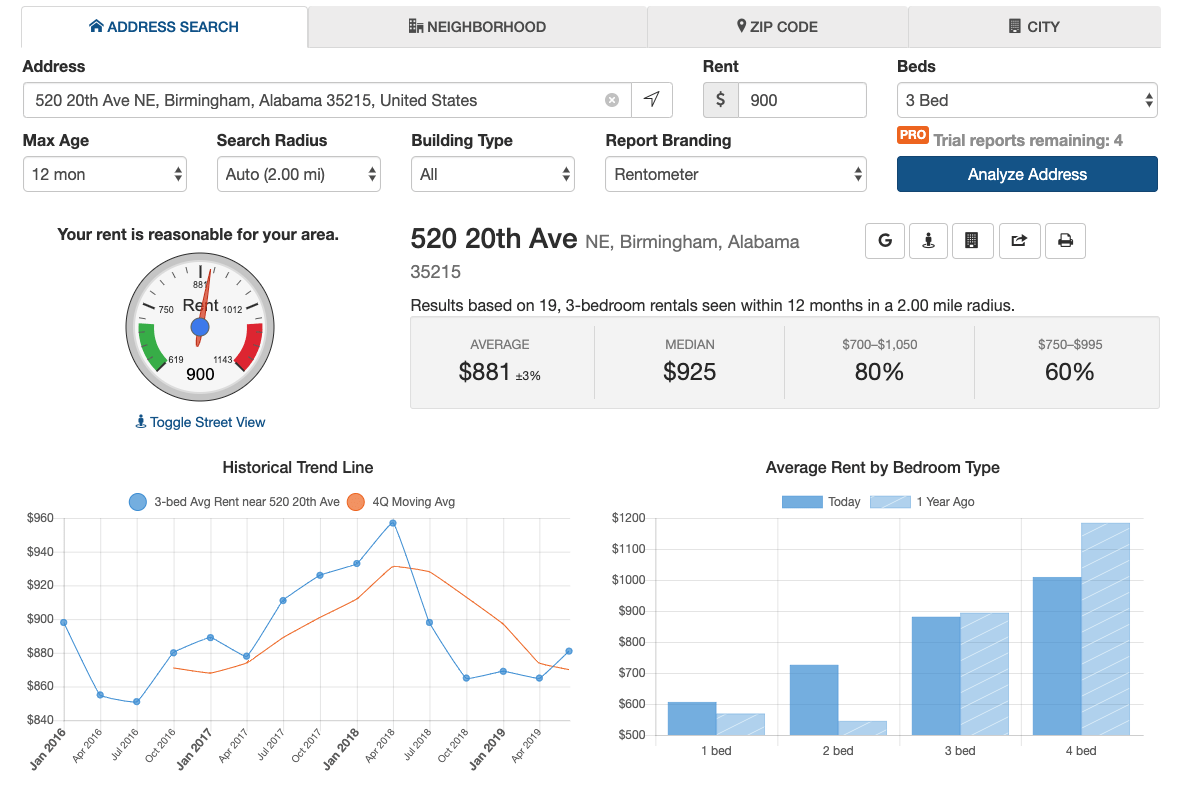
Also in primary markets and luxury classes, the lows are a lot lower than secondary/tertiary markets for example in times of trouble a home in Hawaii might go down 20% value whereas a more boring market like Birmingham might lose 5-10% value or even stay the same because it was not a high appreciation frenzy market to begin with anyway.
People talk about covering yourself with a proper loan to value (LTV) In case you have to take over the property from the flipper/developer who screwed up but when things go bad it’s a street fight and LTV means nothing. The more practical and likely exit strategy without having to pay more friction/transaction costs is to rent the property out to recoup some losses.
By the way, if you have $30,000 why not begin with the end in mind and start purchasing cashflowing assets now – start with a turnkey rental!
2) Commercial > Residential – Residential properties are so subjective and require an emotional buyer on the end to pay a crazy price. Think House-hunters on HGTV where a couple sets out to buy those dream homes and you watch as one of the spouses manipulates the other to buy the one they want regardless of price. It is great when it works as the developer (as a debt investor you don’t partake in the extra profits anyway).
But the sale price it’s really outside your control as it is dictated by what other houses are selling for. I prefer math to dictate when our sales price goes as a multiple of the income minus expenses that the property cashflows. This is something we have control over and can have multiple exit strategies.
3) Alright, the development plan goes perfectly and gets a great sales price. Unfortunately as mentioned before, you as the debt investor don’t see any of the upside.
Here are the problems:
a) your yield stops as you have to scramble for the next deal to go into, and
b) all these gains are active income taxes at the highest tax amounts. You don’t get any of the sweet benefits of depreciation or bonus depreciation from doing cost segregation on a bigger deal as an LP.
Check out our Guide to Syndications.
4) Better options – when you get one or two syndicated deals from a plethora of asset classes outside the most competitive realm of single-family home flipping that offer existing cashflow and value-add opportunities where total returns range from 80-120% in 5 years then it blows 8-12% first lien deals out of the water in terms of risk-adjusted returns.
If you are looking for even lower risk investments in the same 8-12% range I would suggest triple net leases with stable multi-million dollar companies like Starbucks, doctor/dentist offices, or Walgreens. In addition, for even more non-correlated assets consider life settlements where you are getting on the sure thing… Death.
Frequently Asked Questions (FAQ)
Who’s the manager of the money and transaction? And capital back after one year? K-1?
You are lending money to a flipper to do a rehab and have title to the property. You are a debt investor.
It could take 12 months to 18/24 months but the longer it takes the more you get paid. There is no K1.
Further Resources
Testimonials
“One of the first things I looked into to get away from Wall Street were the many Crowdfunding sites out there but I just was not into paying another middleman to give me a false sense of security and take a chunk of the profits from the operator and me the investor. Text the word “money” to 314-665-1767. These lending opportunities are exclusive to The Wealth Elevator investor community members to power operators I trust and will put my brand on the line with.”
“My $40K loss in my first Limited Partner role back in 2013 taught me to not work with just any guy you don’t know, like, or trust. The problem is that most investors just don’t have many options and they jump into a deal out of scarcity. Introducing Simple Passive Lending for access to 1st lien short-term lending opportunities backed with a secure note to a property. For more info, text the word “money” to 314-665-1767.”
“The Wealth Elevator investor community is a free investor club where we work together to crowdsource deals and do due diligence together. Most members in our group graduate to Passive Investors but some investors with who I have built a relationship over the past years have graduated to active operator status. To back our own members in something they have found their true calling in I am rolling out Simple Passive Lending to learn more text the word “money” to 314-665-1767.”
About the author
Lane Kawaoka, PE, is the founder of The Wealth Elevator and the author of two Amazon bestselling books, The Wealth Elevator and Simple Passive Cashflow. He spent 12 years as an engineer, bought his first rental in 2009, and left his job in 2019. He built his base in real estate and today is a general partner, operator and fund manager working with a community of accredited investors across real estate, oil and gas, and private companies. His track record: $2.1B of past real estate acquisitions, 10,000+ units acquired, 65+ projects, and $230M+ raised.
This site is free education for accredited investors and high-income professionals whose net worth sits mostly in stocks, a 401(k) and a salary. Start with the guides, the podcast or an event.
This is educational content, not tax, legal, or investment advice. We are not attorneys, CPAs, or financial planners. Please let us know if you need a referral to a CPA, lawyer, or other vendor here.
