
Many doctors earn a high income and still feel behind, between student debt, taxes and long hours. This page is my take on how physicians at any stage can set a financial goal and work toward it.
Physicians are not the only ones who can issue an Rx (prescription). This will be my financial freedom Rx to them. Whether they are junior professionals or senior professionals it’s never too early or too late to lay down a financial goal. Besides, money is a tool to gain more freedom.
As a doctor, have you ever found yourself in this kind of scenario as well?
Let’s face it! Doctors are misunderstood when it comes to money and finances. Most people think that you’re high income earners (sad to say it comes with high tax as well) in fact, it’s true but mainly depends on specialization and level of seniority.
It isn’t until after spending years in medical school to earn their degrees, the whole residency system, and finally taking the requisite board exams that many physicians will enter the full-time workforce and start making the “big money”.
At that point, there is so much delayed gratification and external expectation that “doctors are rich and has huge wealth” to buy a large house or fancy car.
Sure doctors make good money (more and more going to insurance companies- like dealing with disability insurance and admin), but most people don’t realize they work long hours. The burden of student loan debt, credit card debt, and payments on new houses and cars cut into their income, facing financial uncertainties, and make it hard for many to grow their wealth.
Additional downsides are malpractice suits. Stemming from negligence claims from misdiagnosis, superfluous patient claims, or untimely release. Side note (I am not a lawyer) I believe all doctors should have an international trust and not mess around with flimsy LLCs which I have seen getting blown up all the time or pressured into a bad settlement amount (average malpractice settlement amount was $350k per The National Practitioner Data Bank.)
With those in mind, here are five practical tips to help doctors and medical professionals achieve Financial Freedom.
5 Tips for Physicians to Achieve Financial Freedom
1. Set up a REALISTIC plan.
You entered med school because you planned for it!
In reaching one’s goal whether it be in your career, relationship there must be a plan to set things up for success. The same goes with your finances, there has to be a financial plan (especially if you still have a student loan). Another TIP: Consult a financial advisor who can help you manage your personal finance if you have queries about life insurance, strategies to maximize your Roth IRA for your retirement plan, and all about financial literacy. You have an option to join our syndicate as well. We talk about real estate investing, rental property, asset protection, estate planning, and how high income individuals like you can gain more cash flow and passive income.
Remember, as Benjamin Franklin once said, “If you fail to plan, you are planning to fail.”
2. Stick to your plan, NOT your colleague’s plan.
It’s easy to be disheartened when you compare yourself with others’ financial life. For some, this is a struggle, especially with the booming social media.
I understand, you’ve been deprived for so long! You had a low salary as a trainee or resident, long hours of duty, always on call, no social life, and late-night work. Needless to say, you need to focus on your OWN PLAN towards a better financial future and be able to come up with suitable financial decisions.
It won’t be easy, but it’s achievable, with your determination and disciplined financial practices.
Take note, this won’t be forever!
Once you arranged your financial life, reached financial success, and (if possible) did your retirement planning, you’ll be grateful that you did it!
My effective federal tax rate went down from 29% to 15%, in spite of the fact that my income doubled in 2020. All thanks to you and FOOM!
It's helped me adjust my mindset, learn more about the tax code, and implement effective strategies."
3. Invest in ASSETS & live WITHIN your means.
Never live way beyond your means especially if you’ll be spending your money on liabilities rather than buying assets (real estate investment). Just because you’re earning more than you are used to, as a resident, doesn’t mean you’ll go all the way.
Think about having a comfortable retirement (perhaps an early retirement), what happens if there are scenarios that are beyond your control (disability, death, environmental disaster), being debt-free (or having good debt instead of bad debt), and reaching financial independence.
4. Save MORE than enough.
This is connected to the previous tip that will benefit not only you (for retirement savings or you can become a business owner) but your family as well. If you still cannot afford a luxurious house, rent for the meantime then save and invest the others. If you’re planning to buy your dream Tesla car, afford a modest Honda/ Toyota and let your other money work for you.
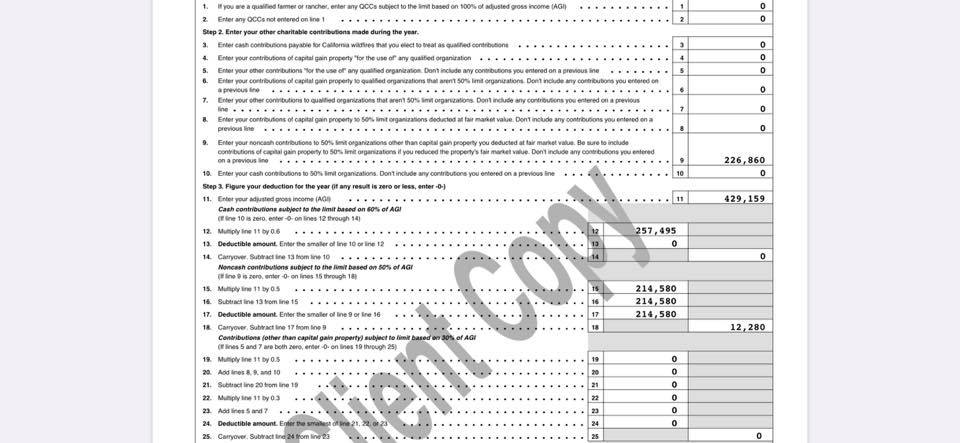
AGI of 429k and 47k taxes paid!
5. Follow REAL experts’ advice.
Beware of those who are pretending to be financial advisor claiming that they will help you obtain your financial independence, reap more money, and secure fiscal peace.
Don’t waste your money on them!
Check on their credibility, talk to some of their clients and ask them how they can help you.
Remember: Diagnose if you’re watching or talking to a real financial expert.
Case Study
I am trying to find a way, and need your insights in becoming a Qualified Real Estate Professional in 2024!
Challenge #1: By law, I need to clock in more hours as an ACTIVE, RE Professional than an emergency physician, i.e 51% vs. 49%. Right?
Challenge #2: I need to clock in 750+ hours of active RE professional work per year, and I know that being an LP in any Nap Cap syndications and/or researching any other PASSIVE investment does NOT qualify me. Right?
Correct, you are not a managing member and do not have carried interest (not guaranteeing the loan or much skin on the line).
Challenge #3: Do I have to become a state licensed real estate agent in Texas, and start listing SMF’s to qualify for that active work, or can you think of any other activity that may qualify me instead?
This has nothing to do with Active Participation in your portfolio. This is a common misnomer.
Challenge #4: I have a friend who owns and manages his own, 40+ SFH’s, in 3 different states. If I help him manage these homes or help him look for future properties to purchase (and add to his portfolio), will that qualify me as an RE prof.?
This has nothing to do with Active Participation in your portfolio.
Challenge #5: Does becoming a GP in any future syndications qualify me as a RE Professional? Will those future dividends/proceeds now become active income vs. passive?
This might be a possibility here. Consult your CPA and coach them through your logic. This is where the Family Office Ohana Mastermind comes in, where many people are educating and sharing best practices to set up their family affairs and bring their CPA/Tax professionals on board.
Challenge #6: In general, remind me again, why can’t my passive gains in my ER Hospital ownerships can NOT offset, dollar for dollar, the K1 losses from my passive MFH syndications?
Coaching Calls
About the author
Lane Kawaoka, PE, is the founder of The Wealth Elevator and the author of two Amazon bestselling books, The Wealth Elevator and Simple Passive Cashflow. He spent 12 years as an engineer, bought his first rental in 2009, and left his job in 2019. He built his base in real estate and today is a general partner, operator and fund manager working with a community of accredited investors across real estate, oil and gas, and private companies. His track record: $2.1B of past real estate acquisitions, 10,000+ units acquired, 65+ projects, and $230M+ raised.
This site is free education for accredited investors and high-income professionals whose net worth sits mostly in stocks, a 401(k) and a salary. Start with the guides, the podcast or an event.
This is educational content, not tax, legal, or investment advice. We are not attorneys, CPAs, or financial planners. Please let us know if you need a referral to a CPA, lawyer, or other vendor here.
